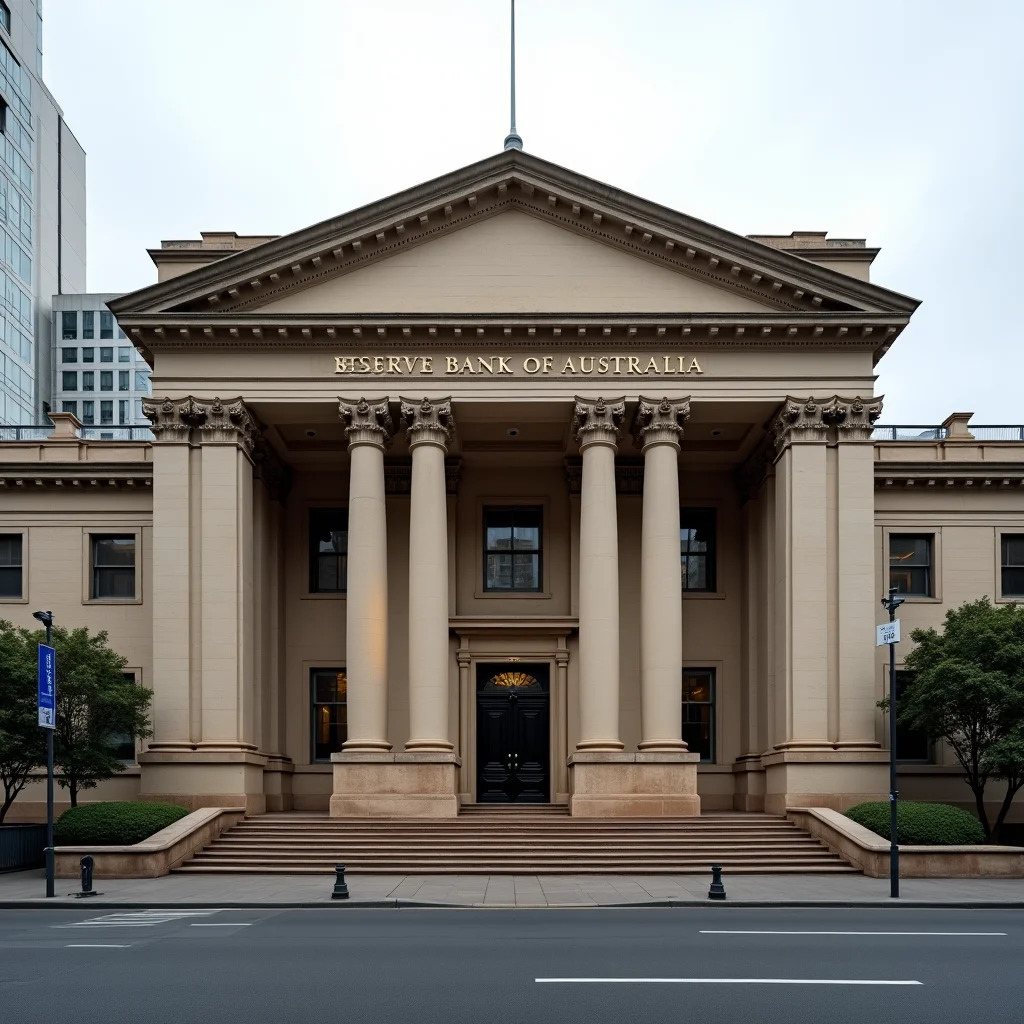
According to REA Group, the Reserve Bank of Australia issued a stark assessment on 27 July 2026: a fundamental lack of understanding about how interest rates and inflation intersect is actively hurting Australian households. On the same day, a Sydney auctioneer declared it the worst day of his 30-year career, with multiple auctions drawing zero bidder interest. Together, these two data points crystallise the central question every Australian property investor must answer at the RBA's current 4.35% cash rate: does residential property still outperform equities, fixed income, and cash when the cost of leverage is this high and buyer confidence is fracturing?
The RBA's Inflation Warning and What It Means for Property Returns
The RBA's financial literacy concern is not abstract — it has direct consequences for how investors calculate real returns across asset classes. When households misunderstand the relationship between inflation and interest rates, they tend to underestimate the true cost of holding leveraged property in a high-rate environment. At 4.35%, the cash rate sits at its highest sustained level in over a decade, and REA Group reported on 27 July 2026 that mortgage lodgements have collapsed in the wake of RBA moves and the federal budget, confirming that credit demand is responding to rate pressure even if headline prices have not universally fallen.
For broader market context, see Bubblepedia's historical Australian property bubble analysis.
The critical distinction for property investors is between nominal and real returns. If Australian residential property is delivering nominal capital growth of, say, 4.5% in Toorak (VIC) or 3.9% in Prahran (VIC), and the risk-free cash rate is 4.35%, the real premium for taking on illiquid, leveraged, single-asset exposure is marginal at best in those markets. This is precisely the misperception the RBA flagged: households treating gross property appreciation as equivalent to net investment return without accounting for financing costs, inflation-adjusted purchasing power, or opportunity cost against liquid assets.
For investors comparing property against the ASX 200 — which has historically delivered approximately 9–10% total returns including dividends over the long run — the calculus in underperforming markets is now unfavourable. Melbourne suburbs like Dandenong (2.3% annual growth, $680,000 median) and Reservoir (2.8% annual growth, $880,000 median) are delivering capital growth that sits below both the cash rate and long-run equity benchmarks, before financing costs are deducted.
Sydney's Auction Collapse vs WA's 15% Growth: A State-by-State Return Divide
The Sydney auction data from 27 July 2026 is the most visible manifestation of how the 4.35% cash rate is fracturing property's competitive position against other asset classes. With auctioneers reporting zero bidder turnout at multiple campaigns, the auction method — which depends on competitive tension to establish market-clearing prices — is effectively broken in parts of the Sydney market. Port Macquarie (NSW) recorded a 46% clearance rate with properties sitting on market for 48 days and annual growth of just 3.5% at an $850,000 median. Ballina (NSW) similarly posted 4.0% annual growth with a 47% clearance rate and 45 days on market. These are not investment-grade returns at the current cost of debt.
Western Australia presents an entirely different proposition. Nedlands posted 15% annual growth at a $2,200,000 median with properties clearing in 15 days and a 65.5% clearance rate. South Perth recorded 13.8% growth at $1,450,000 with a 17-day sales cycle. Mandurah delivered 10.5% growth at a $550,000 entry point — still well above the cash rate in nominal terms. These WA figures represent genuine outperformance of equities on a pure capital growth basis, though investors must still account for rental yield, holding costs, and the illiquidity premium relative to an ASX ETF or term deposit.
Western Australia's top-performing suburbs recorded 10.5%–15% annual capital growth in July 2026, outperforming the RBA's 4.35% cash rate by 6.15–10.65 percentage points — a spread that no fixed-income product currently matches. Victoria's comparable suburbs delivered 2.3%–4.5%, producing near-zero or negative real returns after financing costs.
Queensland sits in the middle of this state divide. West End (QLD) posted 8.8% annual growth at a $1,350,000 median with a 22-day sales cycle, and Maroochydore recorded 8.5% growth at $1,050,000 with 28 days on market. These figures comfortably exceed the cash rate and offer a genuine premium over fixed income — though not the outsized spread that WA metro currently delivers.
Yield, Growth, and the Financing Cost Squeeze
The property versus other assets debate in a 4.35% rate environment cannot be resolved by capital growth alone. Gross rental yield must be added to the equation, and here Australian residential property has historically traded at yields of 3–4% in major cities — substantially below the cash rate. This means the total return case for property investment now depends almost entirely on capital appreciation, with the income component insufficient to cover financing costs on a typical 80% LVR loan priced above 6%.
The practical implication: a property investor buying at Randwick's $2,400,000 median with a 20% deposit is carrying approximately $1,920,000 in debt. At a variable rate of roughly 6.2% (above the cash rate), annual interest costs approach $119,000. If Randwick's 5.6% annual growth ($134,400 in dollar terms) is the primary return driver, the net capital gain after interest — before rates, maintenance, agent fees, and vacancy — is marginal at best. An equivalent $480,000 cash equity position in a diversified ASX 200 index fund at 9–10% total return (with no leverage and full liquidity) produces comparable or superior net outcomes without concentration risk.
This is not a theoretical argument — it is the lived experience that the RBA's literacy warning points toward. Many property investors are not modelling total return inclusive of financing costs; they are anchoring to gross capital growth as if it were equivalent to the return on an unlevered asset. Understanding the full cost structure is covered in the Property Cycle Timing — Using Data to Make Better Decisions guide, which outlines how leading indicators like clearance rates and days on market signal market shifts 2–6 months before price movements materialise.
Where Property Still Beats Other Asset Classes on a Risk-Adjusted Basis
The case for residential property as the superior asset class is not dead — it is geographically concentrated. In WA's metro markets, the combination of capital growth well above the cash rate, tight days-on-market figures (Nedlands at 15 days, South Perth at 17 days), and clearance rates above 63% indicates genuine supply-demand imbalance that equities cannot replicate. An investor who purchased in Nedlands twelve months ago captured 15% capital appreciation on an asset that is also generating rental income — a combined return structure that no ASX-listed equivalent delivered in the same period with equivalent leverage.
The comparison also shifts materially when leverage is applied in the investor's favour rather than against them. A $440,000 deposit on a $2,200,000 Nedlands property that appreciates 15% generates $330,000 in capital gain — a 75% return on equity before financing costs, though a gross figure investors must net down carefully. No liquid asset class produces comparable leveraged returns legally available to retail investors in Australia. This leverage premium is property's structural advantage over shares, cash, and bonds — and it explains why, despite the RBA's rate settings, transaction volumes in WA remain tight relative to stock.
For a broader perspective on how these dynamics compare internationally, international property market analysis shows that Australia's state-by-state divergence mirrors patterns seen in other two-speed economies where resource-driven states outpace financial centres during tightening cycles. The Australian Property Forum's analysis of SA suburbs recording price falls in July 2026 further demonstrates that even within states, the gap between performing and underperforming micro-markets is widening — a pattern that demands suburb-level due diligence rather than state-level generalisation.
What the Data Signals for Investors Allocating Capital in the Near Term
The convergence of the RBA's inflation literacy warning, Sydney's worst auction day in three decades, and collapsing mortgage lodgements creates a clear signal for investors comparing asset classes: the property premium over equities and fixed income is now highly location-dependent and only unambiguously positive in WA metro and select QLD markets. Victoria's sub-5% capital growth suburbs — including Dandenong at 2.3%, Reservoir at 2.8%, and Prahran at 3.9% — are delivering returns that sit below or barely above the cash rate before any financing costs are applied.
Investors with existing Melbourne or regional NSW exposure should model current total returns inclusive of debt servicing against the alternative of reducing leverage and reallocating to liquid income-producing assets at today's rates. Those evaluating new purchases face a binary: enter WA or QLD markets where growth still materially exceeds the cash rate, or wait for rate reductions to restore the yield gap that makes leveraged property universally competitive. The RBA's own data signals that household misunderstanding of this calculus is widespread — investors who model it correctly hold a genuine analytical edge entering the second half of 2026.

